6.2 The Kelly criterion#
The Kelly criterion determines the size of a bet in a repeated game with binary outcomes. The analysis was proposed in 1956 by John Kelly at Bell Laboratories. Kelly identified an analogy between gambling on binary outcomes and Claude Shannon’s work on encoding information for transmission on noisy channels. Kelly used the analogy to show
The maximum exponential rate of growth of the gambler’s capital is equal to the rate of transmission of information over the channel.
This idea actually predates Kelly. In 1738, Daniel Bernoulli offered a resolution to the St. Petersburg paradox proposed by his cousin, Nicholas Bernoulli. The resolution was to allocate bets among alternative outcomes to produce the highest geometric mean of returns. Kelly’s analysis has been popularized by William Poundstone in his book “Fortune’s Formula”, and picked up by gamblers with colorful adventures in Las Vegas by early adopters though the result lay in obscurity among investors until much later.
This notebook presents solutions to Kelly’s problem using exponential cones. A significant feature of this notebook is the inclusion of risk constraints recently proposed by Boyd and coworkers. These notes are based on recent papers by Busseti, Ryu, and Boyd (2016), Fu, Narasimhan, and Boyd (2017). Additional bibliographic notes are provided at the end of the notebook.
See Solvers used in this book for installation, licensing and the differences between solver interfaces.
import sys, os

if 'google.colab' in sys.modules:
    %pip install idaes-pse --pre >/dev/null 2>/dev/null
    !idaes get-extensions --to ./bin
    os.environ['PATH'] += os.pathsep + os.path.abspath('bin')
    solver = "ipopt"
else:
    solver = "mosek_direct"

import pyomo.kernel as pmo
from pyomo.opt import assert_optimal_termination
SOLVER = pmo.SolverFactory(solver)

assert SOLVER.available(), f"Solver {solver} is not available."
Optimal log growth#
The problem addressed by Kelly is to maximize the rate of growth of an investor’s wealth. At every stage \(n=1,\dots,N\), the gross return \(R_n\) on the investor’s wealth \(W_n\) is given by
After \(N\) stages, this gives
Kelly’s idea was to maximize the mean log return. Intuitively, this objective can be justified as we are simultaneously maximizing the geometric mean return
and the logarithmic utility of terminal wealth
The logarithmic utility provides an element of risk aversion. If the returns \(R_i\) are independent and identically distributed random variables with finite expected log return, then
Thus, maximizing expected log return maximizes expected logarithmic utility of terminal wealth.
Modeling a game with binary outcomes#
The classical presentation of the Kelly Criterion is to consider repeated wagers on a gambling game with binary outcomes. For each stage, a wager of one unit returns \(1+b\) with probability \(p\) if successful, otherwise the wager returns nothing. The number \(b\) refers to the “odds” of game. The problem is to determine what fraction of the gambler’s wealth should be wagered on each instance of the game.
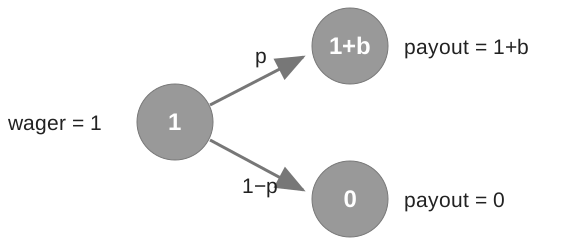
Let \(w\) be the fraction of wealth that is wagered on each instance. Depending on which outcome occurs, the gross return at any stage is
The objective is to maximize the expected log return
The well-known analytical solution \(w^*\) to this problem can be calculated to be
We can use this analytical solution to validate the solution of this problem that we will now obtain using conic optimization.
Conic optimization#
Recall that an exponential cone is a convex set \(\mathbf{K}_{\mathrm{exp}} \) of \(\mathbb{R}^3\) whose points \((r, x, y)\) satisfy the inequality
or the inequalities \(r \geq 0\) and \(y \leq 0\) if \(x=0\).
Introducing two auxiliary variables \(q_1\) and \(q_2\) and taking the exponential of the terms in the objective function, we obtain
and
With these constraints, Kelly’s problem becomes
The following code shows how to obtain the optimal solution using the conic optimization functions of the Pyomo kernel library and the MOSEK solver.
import numpy as np
import matplotlib.pyplot as plt

# parameter values
b = 1.25
p = 0.51


# conic optimization solution to Kelly's problem
def kelly(p, b):
    m = pmo.block()

    # decision variables
    m.q1 = pmo.variable()
    m.q2 = pmo.variable()
    m.w = pmo.variable(lb=0)

    # objective
    m.ElogR = pmo.objective(p * m.q1 + (1 - p) * m.q2, sense=pmo.maximize)

    # conic constraints
    m.t1 = pmo.conic.primal_exponential.as_domain(1 + b * m.w, 1, m.q1)
    m.t2 = pmo.conic.primal_exponential.as_domain(1 - m.w, 1, m.q2)

    return m


m = kelly(p, b)
results = SOLVER.solve(m)
assert_optimal_termination(results)
print(f"Conic optimization solution for w: {m.w(): 0.4f}")

# analytical solution to Kelly's problem
w_analytical = p - (1 - p) / b if p * (b + 1) > 1 else 0
print(f"Analytical solution for w: {w_analytical: 0.4f}")
Conic optimization solution for w:  0.1180
Analytical solution for w:  0.1180
Risk-constrained version of the Kelly’s problem#
Following Busseti, Ryu, and Boyd (2016), we consider the risk-constrained version of the Kelly’s problem, in which we add the constraint
where \(\lambda \geq 0\) is a risk-aversion parameter. For the case with two outcomes \(R_1\) and \(R_2\) with known probabilities \(p_1\) and \(p_2\) considered here, this constraint rewrites as
When \(\lambda=0\) the constraint is always satisfied and no risk-aversion is in effect. Choosing \(\lambda > 0\) requires outcomes with low return to occur with low probability and this effect increases for larger values of \(\lambda\). A feasible solution can always be found by setting the bet size \(w=0\) to give \(R_1 = 1\) and \(R_2 = 1\).
This constraint can be reformulated using exponential cones. Rewriting each term as an exponential gives
We previously introduced two auxiliary real variables \(q_1,q_2 \in \mathbb{R}\) such that \(q_i \leq \log(R_i)\), using which we can reformulate the risk constraint as
Introducing two more non-negative auxiliary variables \(u_1,u_2 \geq 0\) such that \(u_i \geq e^{\log(p_i) - \lambda q_i}\), the risk constraint is given by
For fixed probabilities \(p_1=p\) and \(p_2=1-p\), odds \(b\), and risk-aversion parameter \(\lambda \geq 0\), the risk-constrained Kelly bet solves the following conic optimization problem
The following cell solves this problem with a Pyomo model using the MOSEK solver.
# parameter values
b = 1.25
p = 0.51
lambd = 3


def kelly_rc(p, b, lambd):
    m = pmo.block()

    # decision variables
    m.q1 = pmo.variable()
    m.q2 = pmo.variable()
    m.w = pmo.variable(lb=0)

    # objective
    m.ElogR = pmo.objective(p * m.q1 + (1 - p) * m.q2, sense=pmo.maximize)

    # conic constraints
    m.t1 = pmo.conic.primal_exponential.as_domain(1 + b * m.w, 1, m.q1)
    m.t2 = pmo.conic.primal_exponential.as_domain(1 - m.w, 1, m.q2)

    # risk constraints
    m.u1 = pmo.variable(lb=0)
    m.u2 = pmo.variable(lb=0)
    m.r0 = pmo.constraint(m.u1 + m.u2 <= 1)
    m.r1 = pmo.conic.primal_exponential.as_domain(m.u1, 1, np.log(p) - lambd * m.q1)
    m.r2 = pmo.conic.primal_exponential.as_domain(m.u2, 1, np.log(1 - p) - lambd * m.q2)

    return m


# conic optimization solution to the risk-constrained version of Kelly's problem
m = kelly_rc(p, b, lambd)
results = SOLVER.solve(m)
assert_optimal_termination(results)
print(f"Risk-constrained solution for w: {m.w(): 0.4f}")
Risk-constrained solution for w: 0.0589
Simulation#
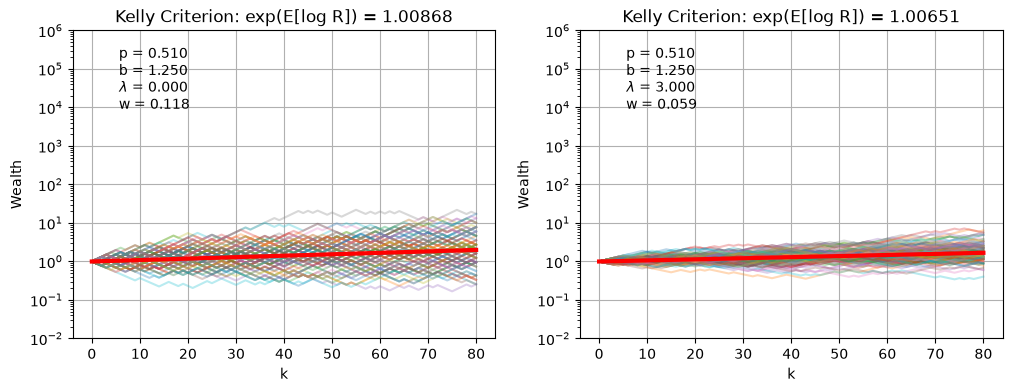
The following cells simulate the performance of the Kelly Criterion both with and without risk constraints. Compare the cases by comparing the log mean growth, which is reduced by presence of risk constraints, and the portfolio draw down for the most pathological cases, which is improved by the presence of risk constraints.
The simulation uses 80 stages by default, including when the optimal expected log growth is zero. When \(p(b+1)\leq 1\), the analytical optimum is not to bet; it remains feasible with the risk constraint.
def kelly_sim(p, b, lambd=0, K=80, ax=None):
    if K is None:
        K = 80
    if not isinstance(K, (int, np.integer)) or K <= 0:
        raise ValueError("K must be a positive number of stages.")
    if p * (b + 1) <= 1:
        # The analytical no-bet optimum also satisfies the risk constraint.
        w = 0.0
    else:
        m = kelly_rc(p, b, lambd)
        results = SOLVER.solve(m)
        assert_optimal_termination(results)
        w = m.w()
    m = p * np.log((1 + b * w)) + (1 - p) * np.log((1 - w))

    if ax is None:
        _, ax = plt.subplots(1, 1)

    # monte carlo simulation and plotting
    for n in range(0, 100):
        W = [1]
        R = [[1 - w, 1 + w * b][z] for z in np.random.binomial(1, p, size=K)]
        R.insert(0, 1)
        ax.semilogy(np.cumprod(R), alpha=0.3)

    ax.semilogy(np.linspace(0, K), np.exp(m * np.linspace(0, K)), "r", lw=3)
    ax.set_title(f"Kelly Criterion: exp(E[log R]) = {np.exp(m):0.5f}")
    s = f" p = {p:0.3f} \n b = {b:0.3f} \n $\\lambda$ = {lambd:0.3f} \n w = {w:0.3f}"
    ax.text(0.1, 0.95, s, transform=ax.transAxes, va="top")
    ax.set_xlabel("k")
    ax.set_ylabel("Wealth")
    ax.grid(True)
    ax.set_ylim(0.01, 1e6)


fig, ax = plt.subplots(1, 2, figsize=(12, 4))

kelly_sim(p, b, lambd=0, K=80, ax=ax[0])
kelly_sim(p, b, lambd=3, K=80, ax=ax[1])
Bibliographic notes#
The Kelly Criterion has been included in many tutorial introductions to finance and probability, and the subject of popular accounts.
Poundstone, W. (2010). Fortune’s formula: The untold story of the scientific betting system that beat the casinos and Wall Street. Hill and Wang. Publisher’s page.
Thorp, E. O. (2017). A man for all markets: From Las Vegas to wall street, how i beat the dealer and the market. Random House.
Thorp, E. O. (2008). The Kelly criterion in blackjack sports betting, and the stock market. In Handbook of asset and liability management (pp. 385-428). North-Holland. Published chapter (2008). Earlier version (revised May 1998), freely available from Occidental College.
The utility of conic optimization to solve problems involving log growth is more recent. Here are some representative papers.
Busseti, E., Ryu, E. K., & Boyd, S. (2016). Risk-constrained Kelly gambling. The Journal of Investing, 25(3), 118-134. https://arxiv.org/pdf/1603.06183.pdf
Fu, A., Narasimhan, B., & Boyd, S. (2017). CVXR: An R package for disciplined convex optimization. arXiv preprint arXiv:1711.07582. https://arxiv.org/abs/1711.07582